A regular briefing for the alternative asset management industry
The continuation vehicle (or CV) has grown from a niche liquidity mechanism into a standard portfolio management tool in private equity, with increasing adoption in other asset classes. Jefferies 2025 Global Secondary Market Review records CVs at roughly 14% of sponsor-backed exits globally last year, up from 5% in 2021.
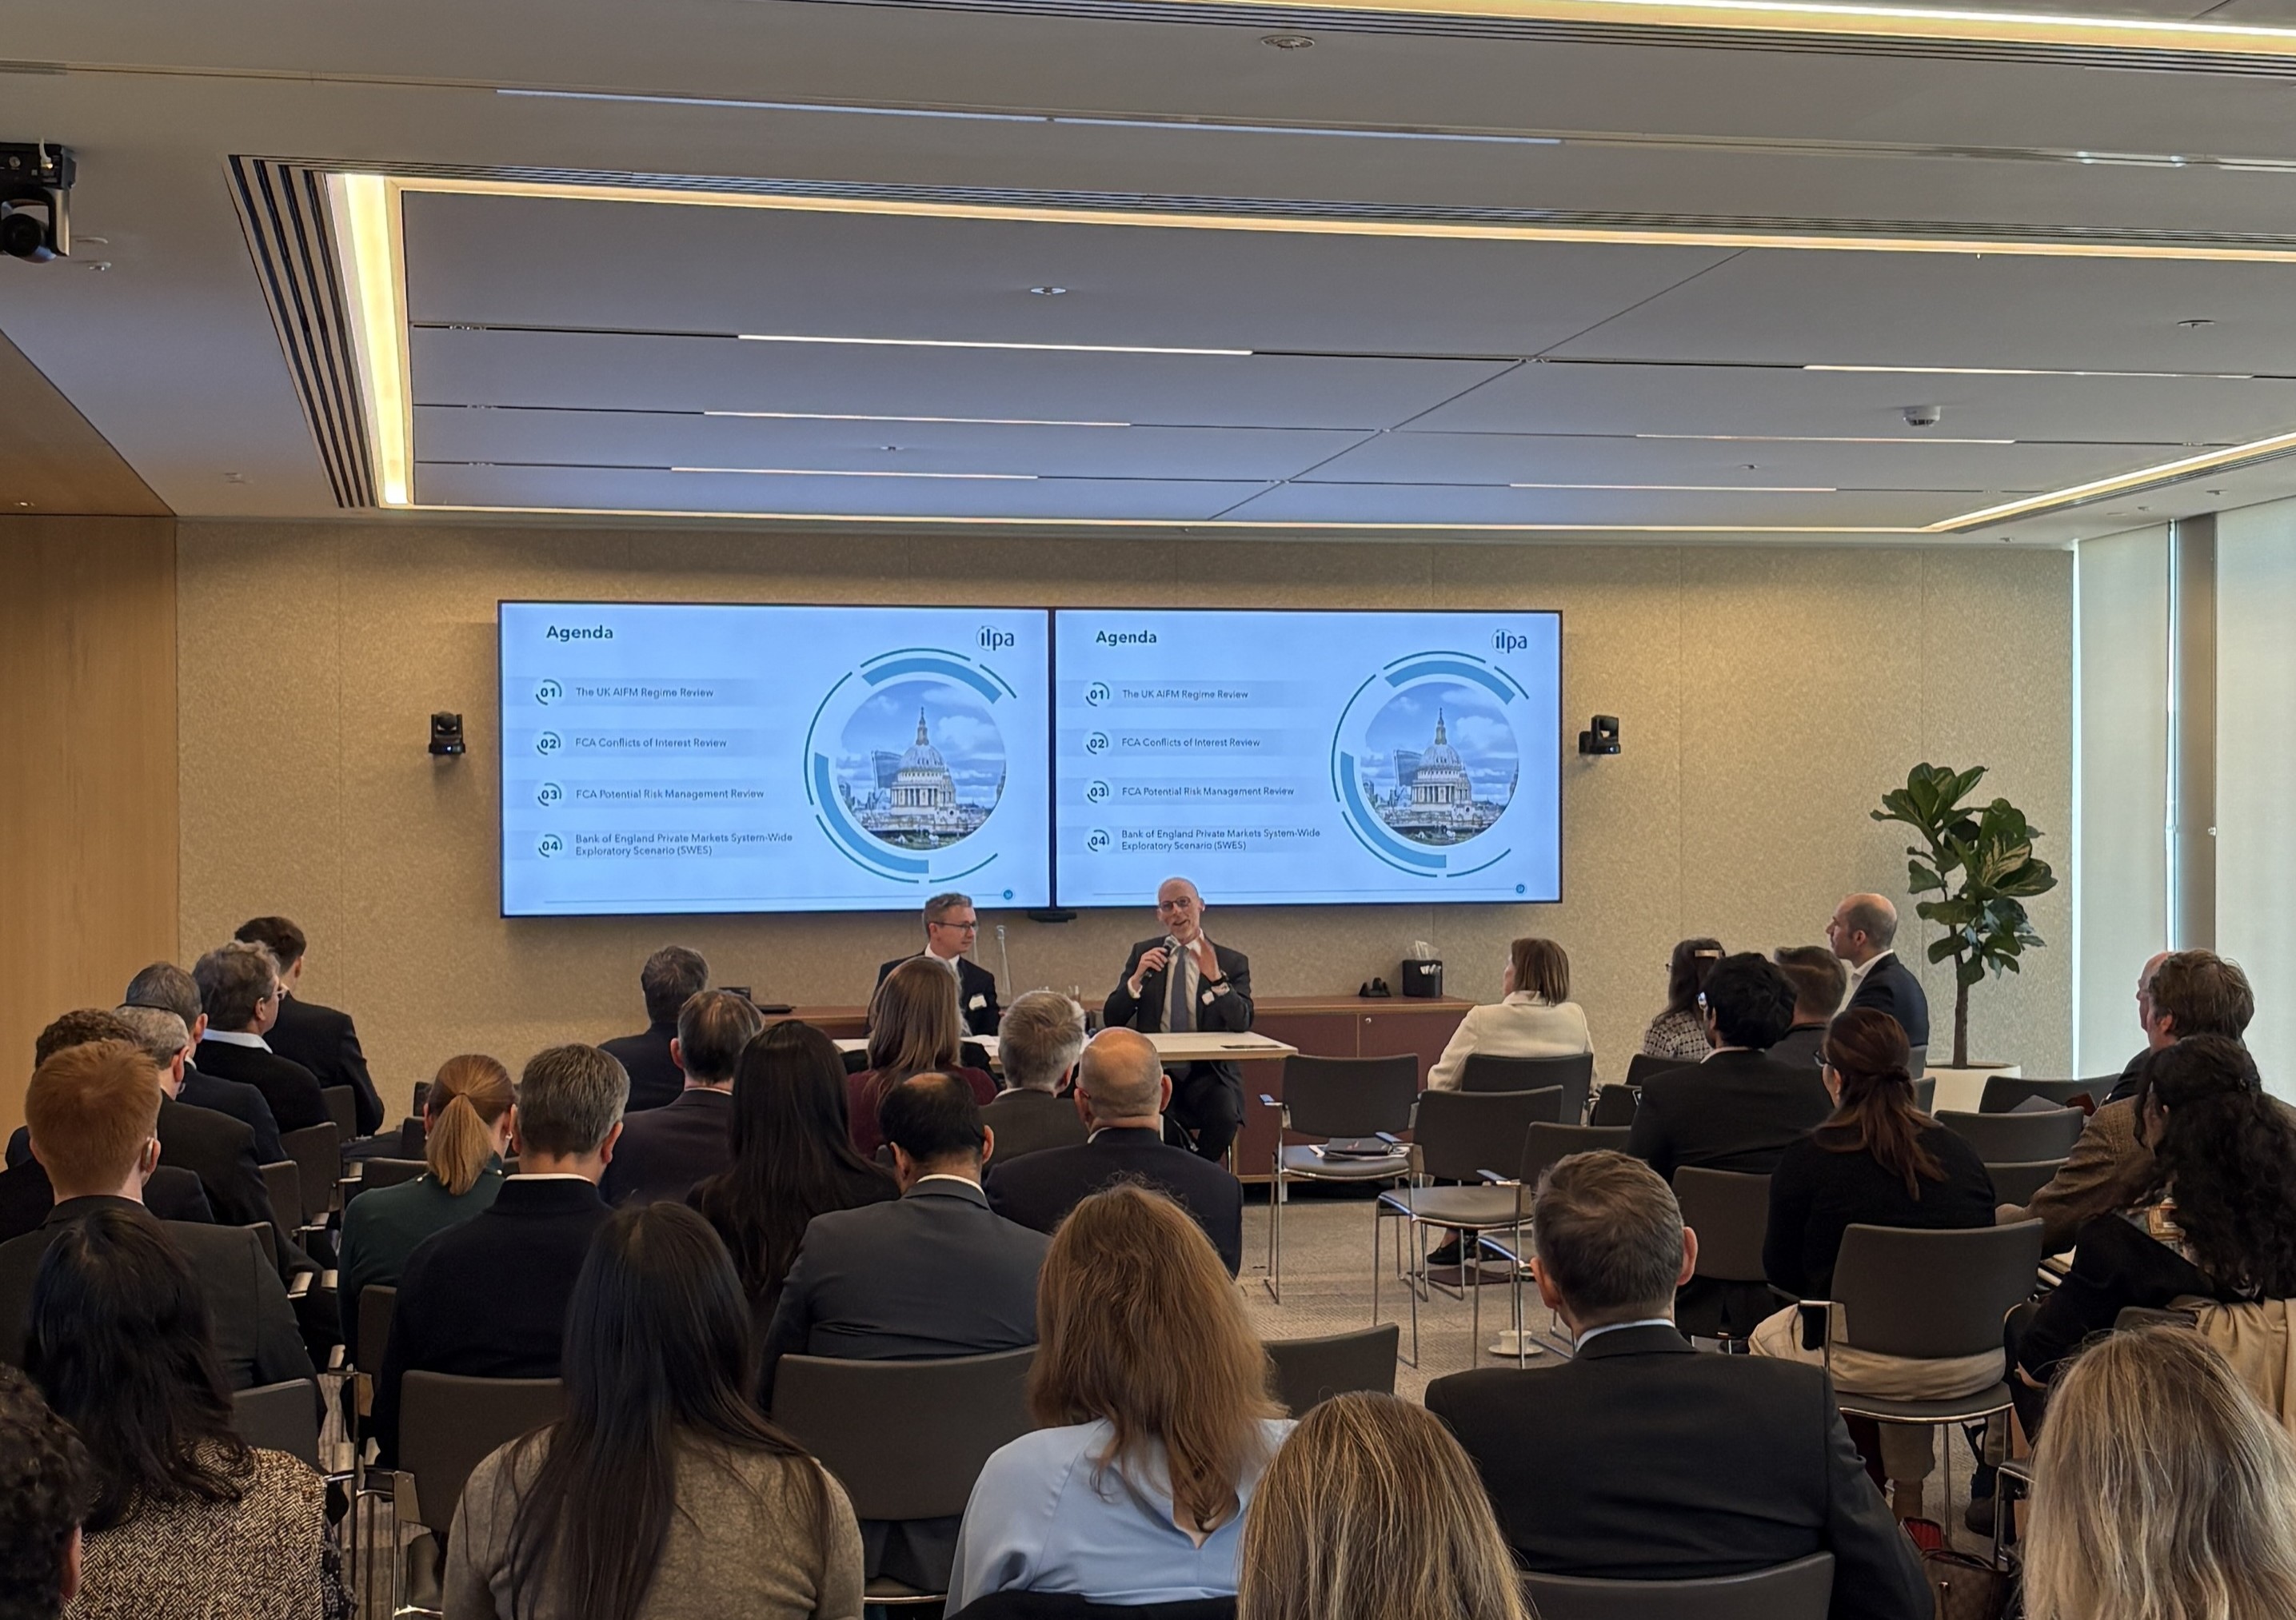
With growth has come increasing scrutiny. As we heard from ILPA (the Institutional Limited Partners Association – the leading industry body for LPs) at a briefing hosted at Travers Smith's offices, LPs have expressed growing concerns about CV misuse.
ILPA has revised its best practice guidance, little more than three years after its 2023 iteration. That's a measure of how quickly the landscape has shifted and is a response to LPs' growing concerns about GP-LP misalignment.
ILPA has retained a principles-based approach, but its guidance is now considerably more detailed. It has shifted tone – removing some of the more prescriptive elements in an earlier draft – to reflect the range and complexity of transactions in the market. Some LPs may balk at the additional flexibility this affords GPs, but ILPA wants GPs to feel able to commit to its principles.
The emphasis nonetheless remains squarely on LP interests: ensuring they sit at the centre of GP decision-making.
The structural conflict at the heart of CVs is well-established. A GP sits on both sides of the transaction – as seller on behalf of the existing fund and as buyer for the new vehicle. The guidance sets out two core principles:
- GPs must explain the rationale for why the CV route serves the best interests of existing LPs; and
- CVs should be a deliberate, considered choice, not a default option, and the GP must demonstrate it offers the best outcome for existing LPs.
The guidance also requires GPs to actively identify, manage and disclose conflicts. Generic disclosures and blanket waivers, it makes clear, are not sufficient or appropriate.